The highlight of the book is the following statement :
Any model should consider the following :
- Transaction Costs,
- Risk,
- Return,
- Market Efficiency
and the objective of a investment strategy should be minimize first two, maximize third and work around the fourth. Liquidity and Taxes are the additional elements to make any model realistic.
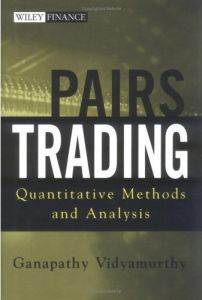
Coming back to what the book is all about,
It is about Alpha, a term used to represent , excess of benchmark returns generated by a fund manager. This book talks about the eternal quest for alpha and poses a lot of interesting questions. It begins with a history of passive indexing strategy and then tries to bring out various perspectives for seeking alpha. Ross’s APT, Markowtiz Portfolio theory, Sharpe’s contribution, Tobin’s Separation theorem are some of the historical aspects which the author brings out in a conversational mode. The rise of managed futures , behavioral finance, quant jocks , var and the hype around it, etc are highlighted in the book.